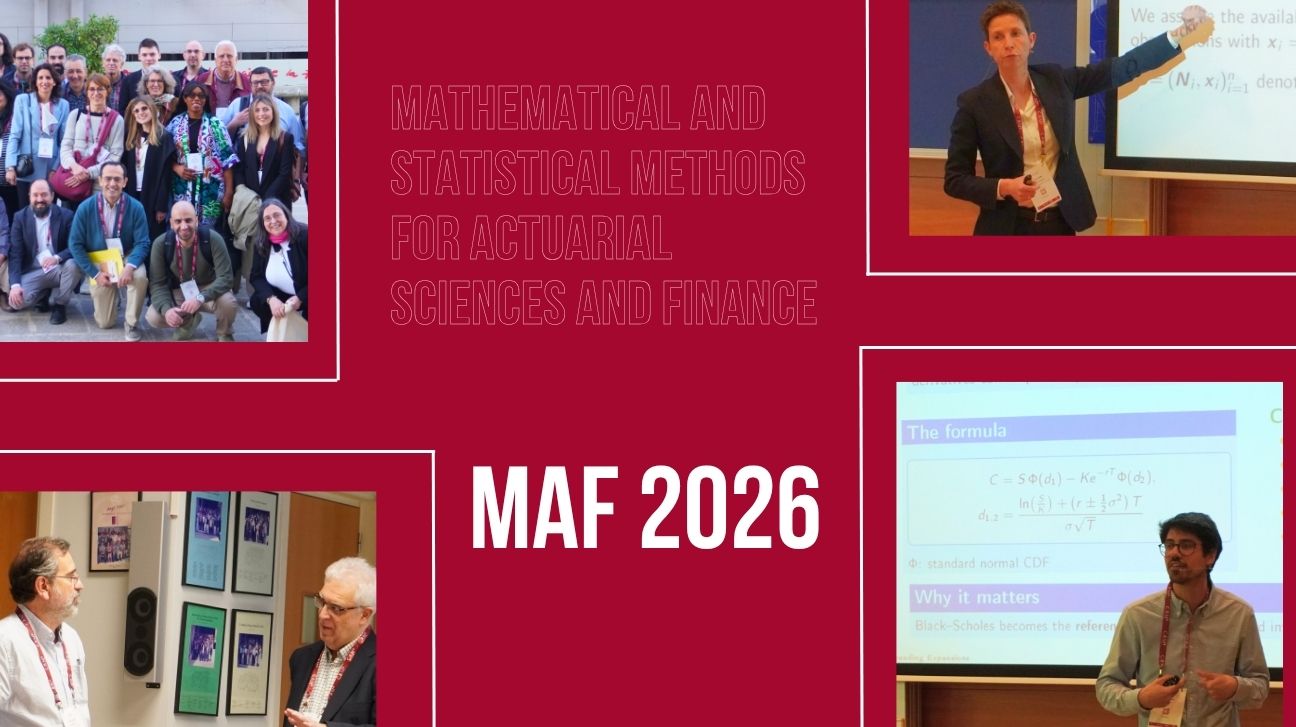
From 8 to 10 April 2026, the Centre de Recerca Matemàtica (CRM) hosted the Conference on Mathematical and Statistical Methods for Actuarial Sciences and Finance (MAF 2026). The conference is an international meeting that brings together mathematicians and statisticians to discuss new theoretical results and applications in actuarial sciences and finance.
The programme combined plenary lectures, parallel sessions organised by thematic areas, and online presentations, reflecting both the diversity of approaches and the international character of the event.
Plenary Speakers
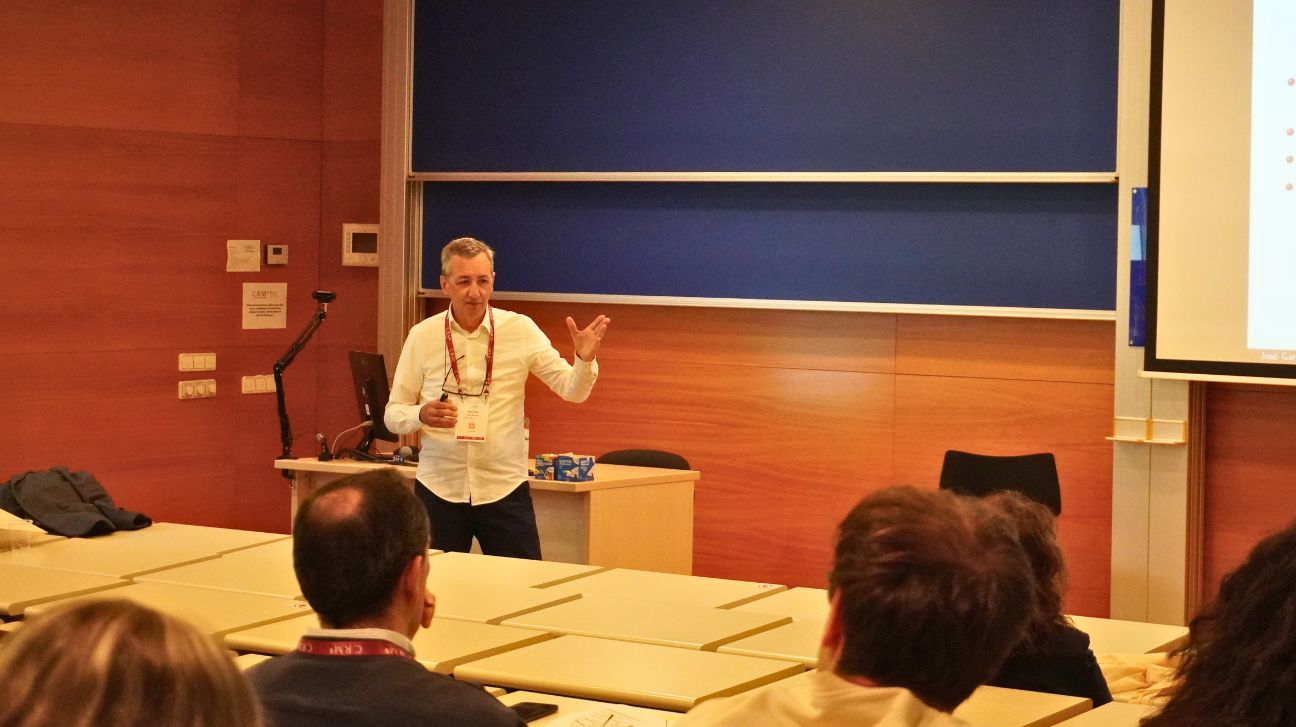
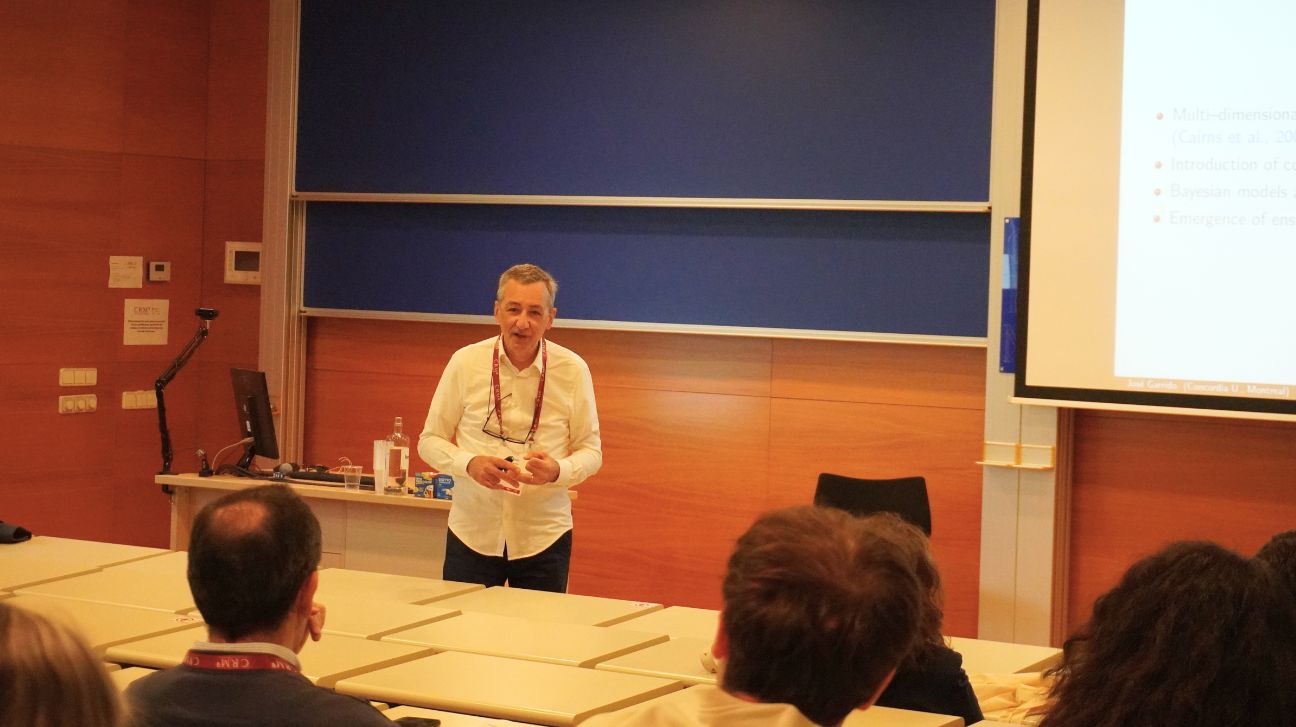
The first plenary lecture was delivered by José Garrido (Concordia University), who presented Accounting for temporal and spatial dependencies in multi-population mortality forecasts: the “transformer” approach. His work extended transformer architectures to incorporate structural dependencies between countries, combining mortality data with exogenous variables. The proposed approach showed a significant improvement in the accuracy of long-term mortality forecasts.
 |
 |
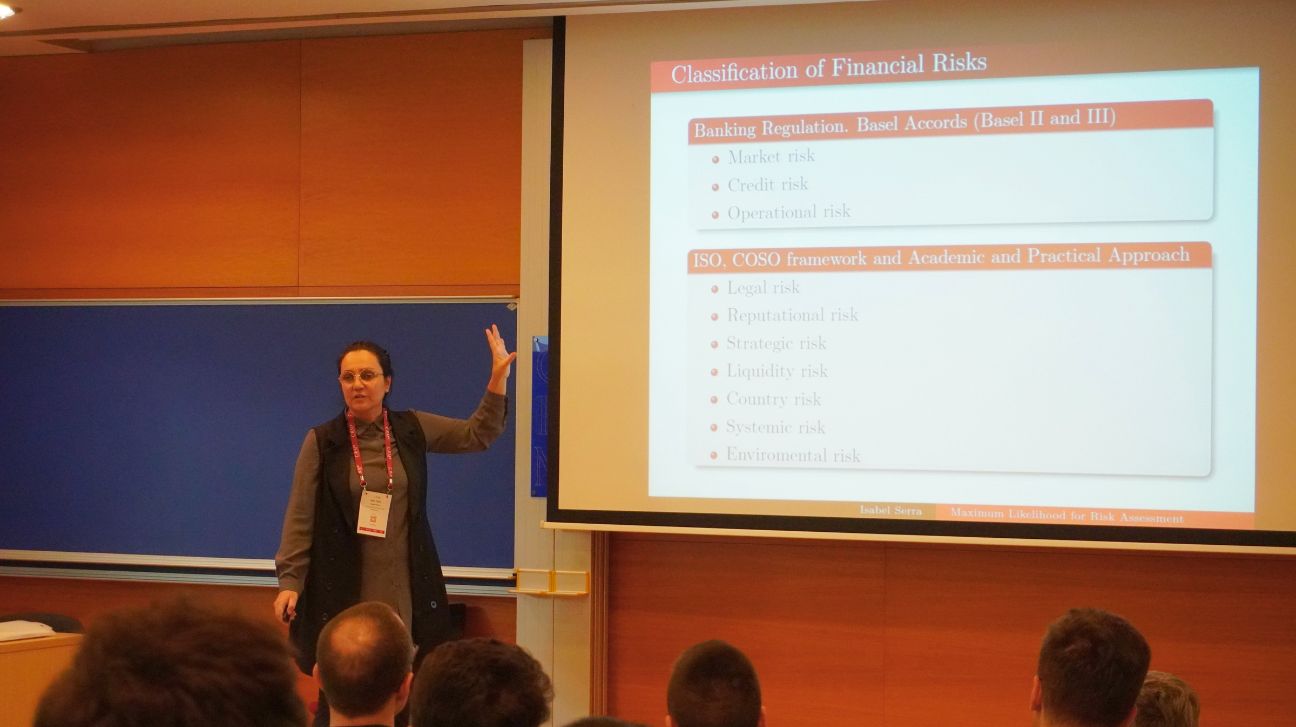
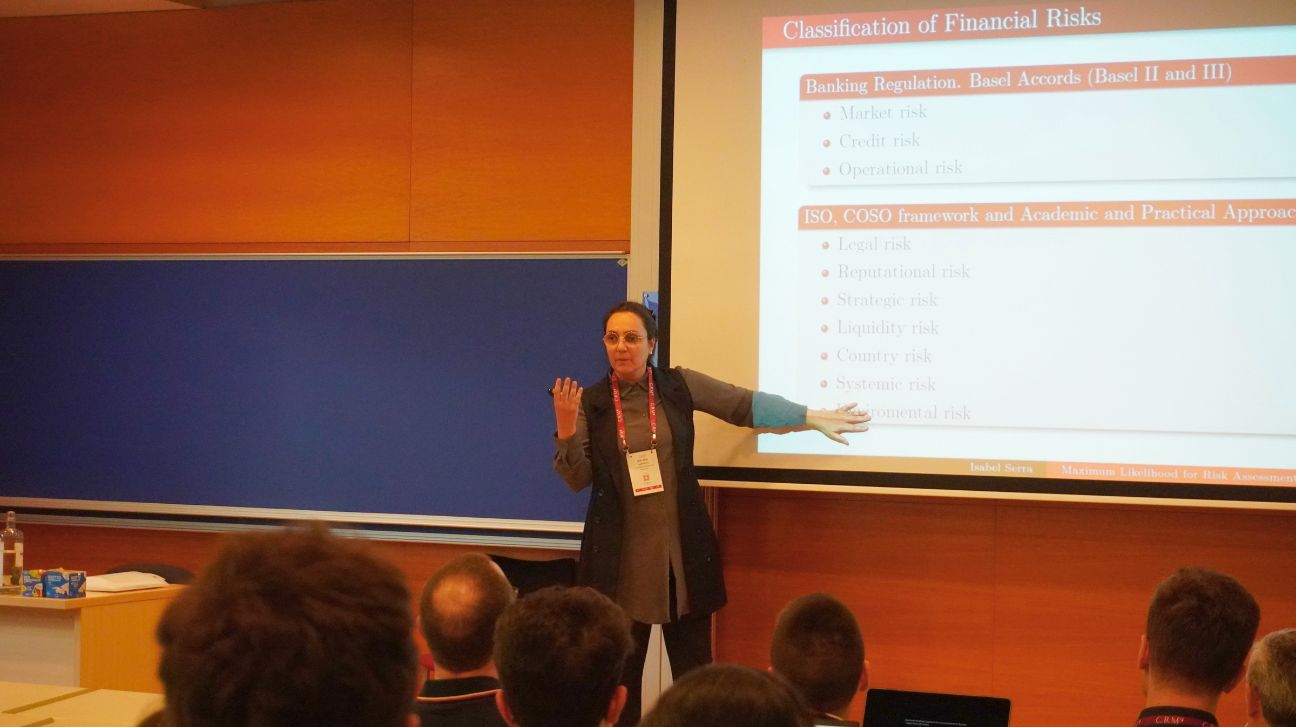
On the same Wednesday, Isabel Serra (Universitat Autònoma de Barcelona) gave the talk Maximum Likelihood Approach for Risk Assessment in Finance, in which she examined financial risk assessment from the perspective of statistical inference of extreme events. Her presentation connected extreme value theory, maximum likelihood estimation, and machine learning, addressing current challenges such as temporal dependence and the presence of mixtures in the data.
 |
 |
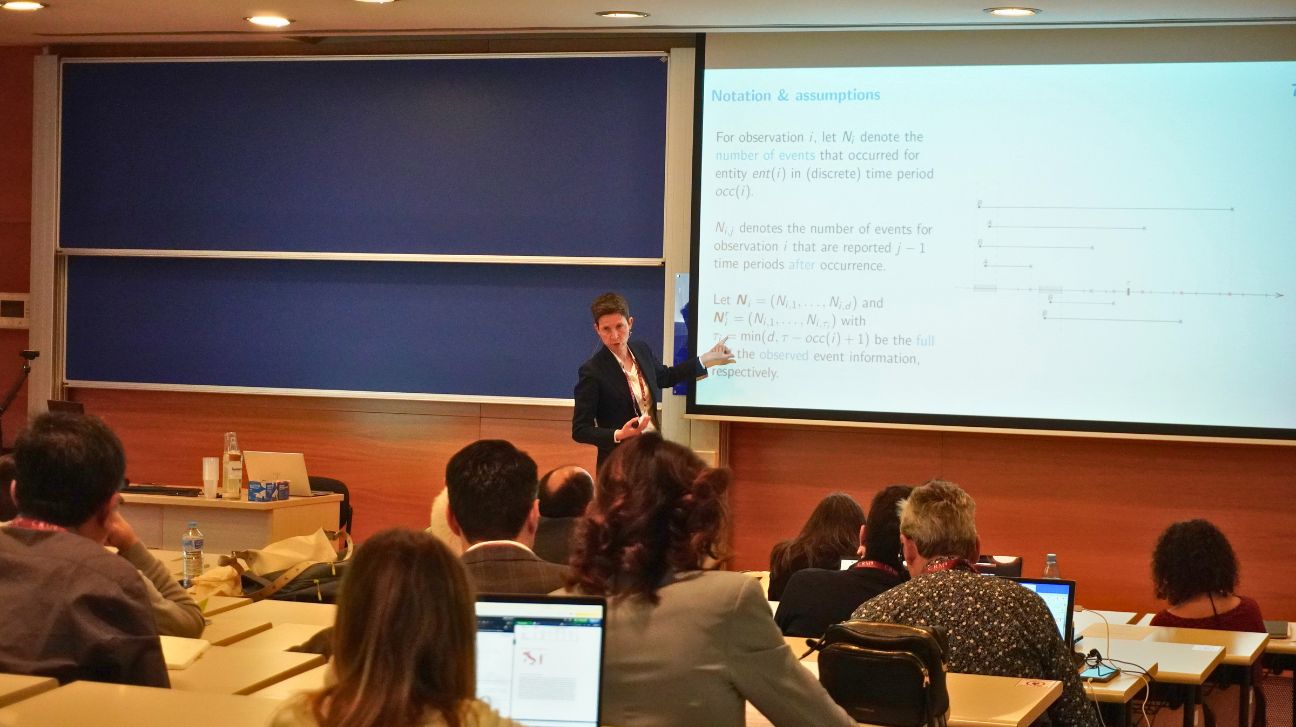
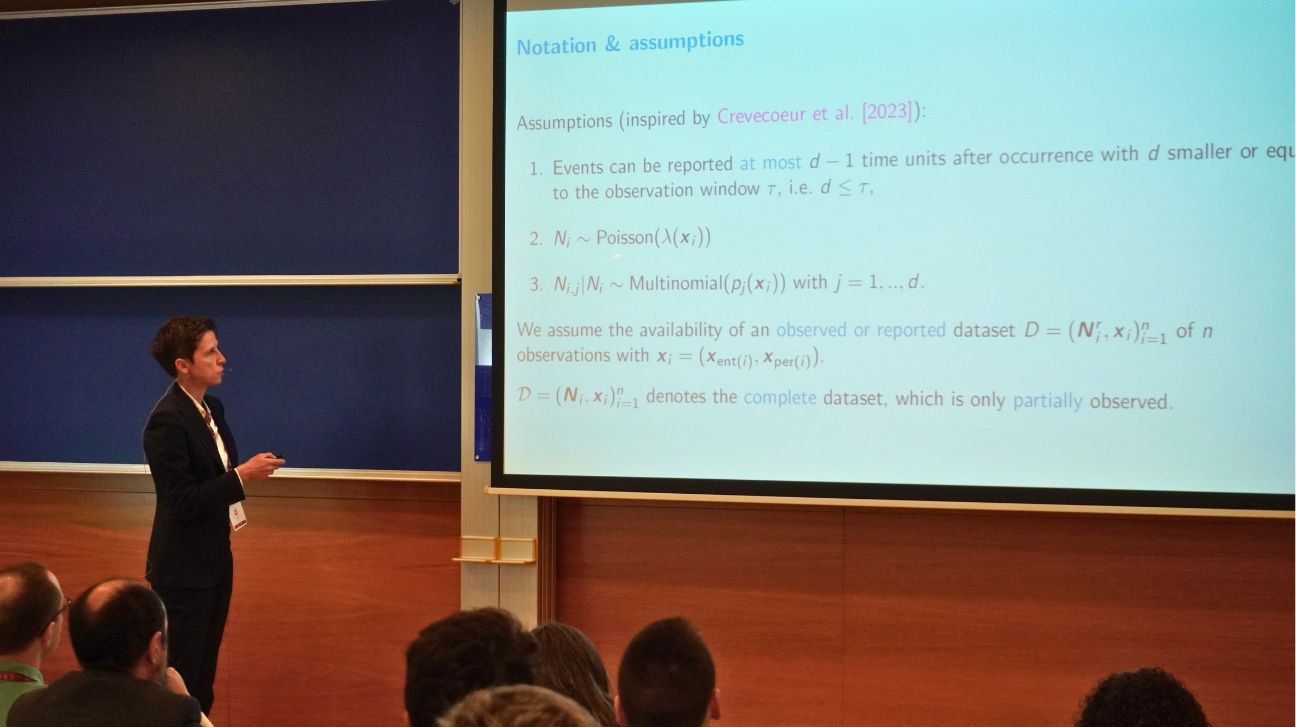
On Thursday, Katrien Antonio (KU Leuven) focused her lecture on Machine Learning in an Expectation–Maximisation Framework for Nowcasting. Starting from the issue of partially observable information and reporting delays, she proposed a framework based on expectation–maximisation that integrates machine learning and deep learning techniques. Her results, particularly relevant in contexts with non-linear effects and high-dimensional data, have direct applications in the modelling of claims related to weather-related events.
 |
 |
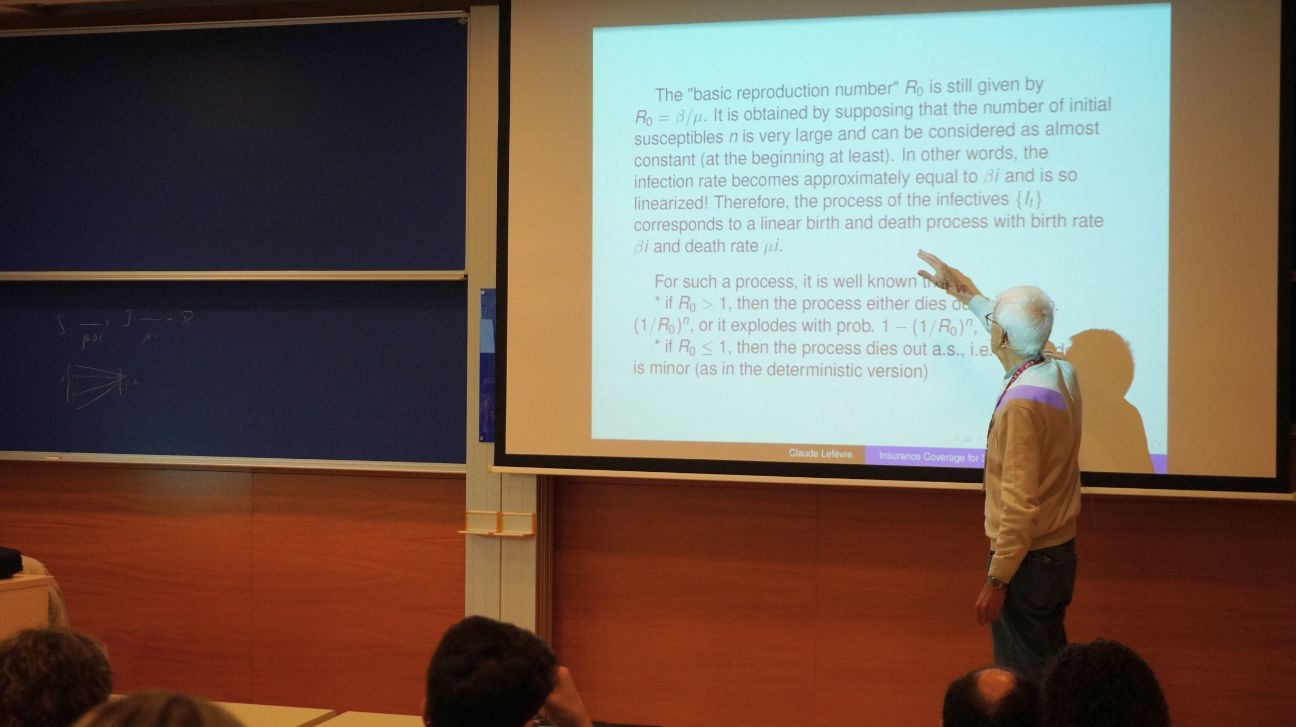
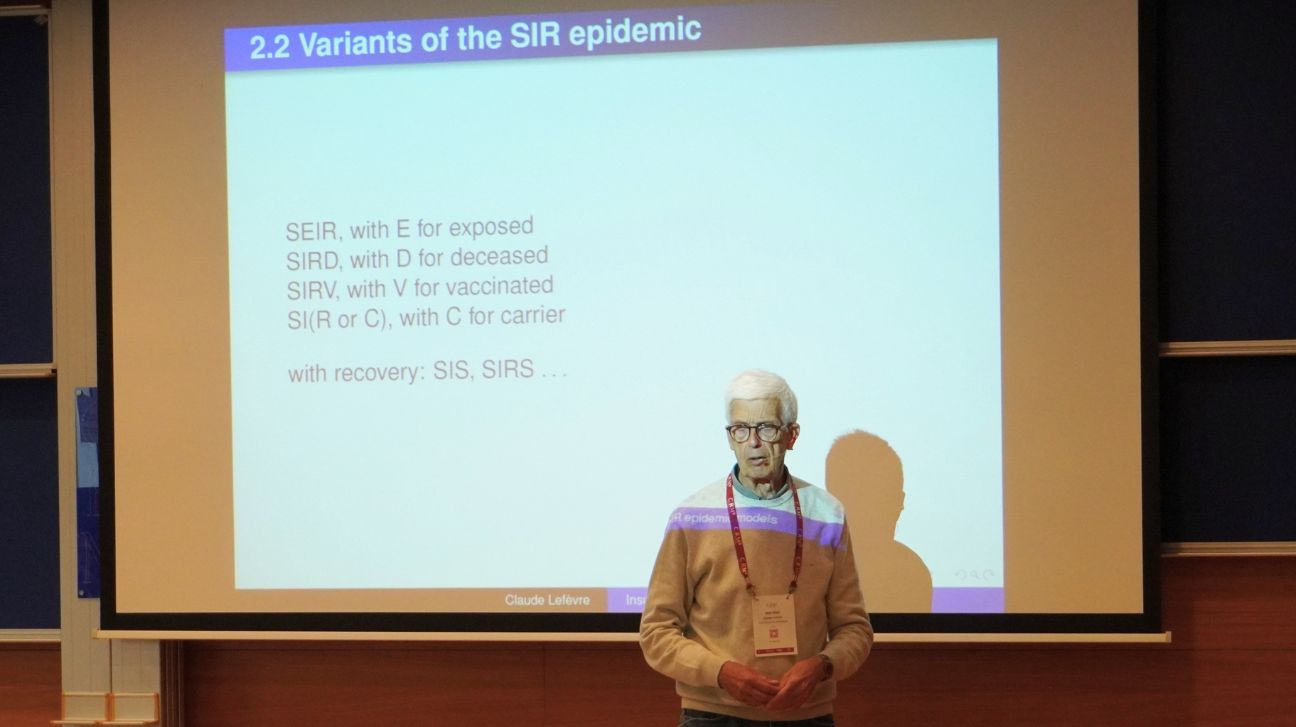
That same day, Claude Lefèvre (Université Libre de Bruxelles) addressed Insurance Coverage for SIR Epidemic Models, centred on stochastic SIR-type models for epidemics. From an actuarial perspective, he analysed premium determination using the equivalence principle, paying particular attention to the total duration of the epidemic process and the expected number of cases. His talk highlighted the mathematical complexity that arises when translating epidemiological models into insurance products.
 |
 |
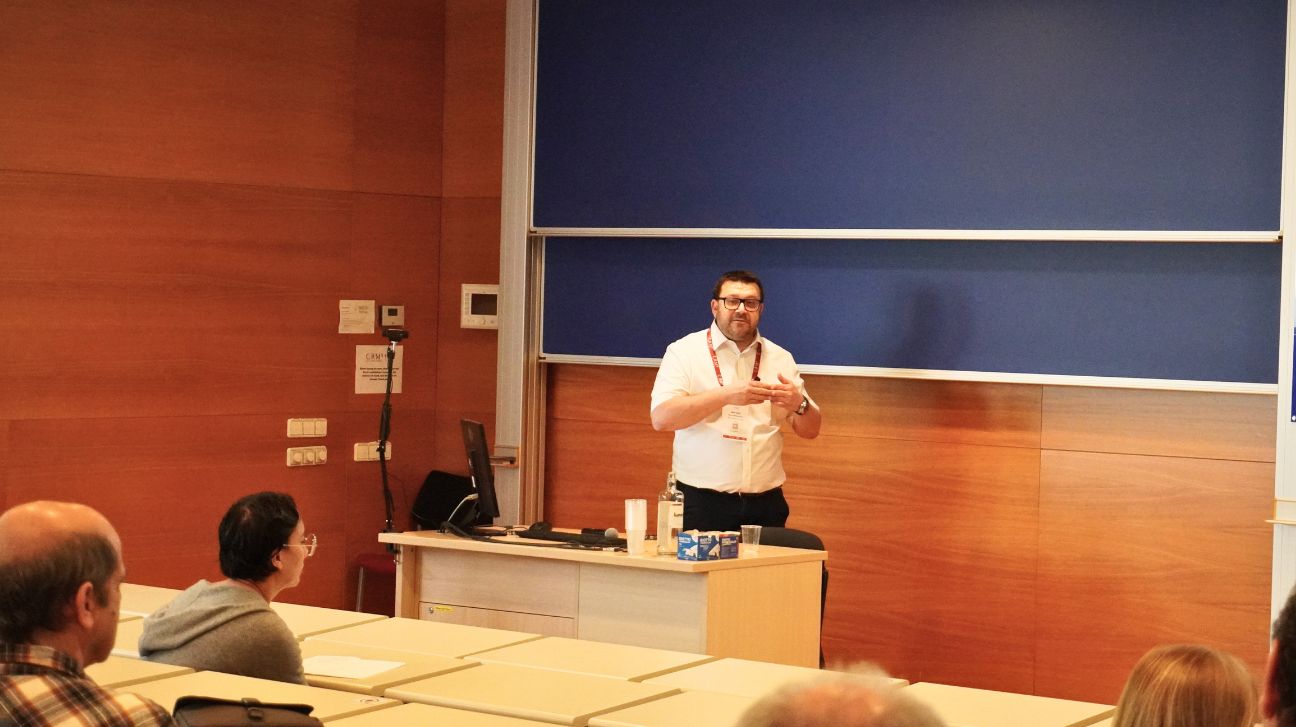
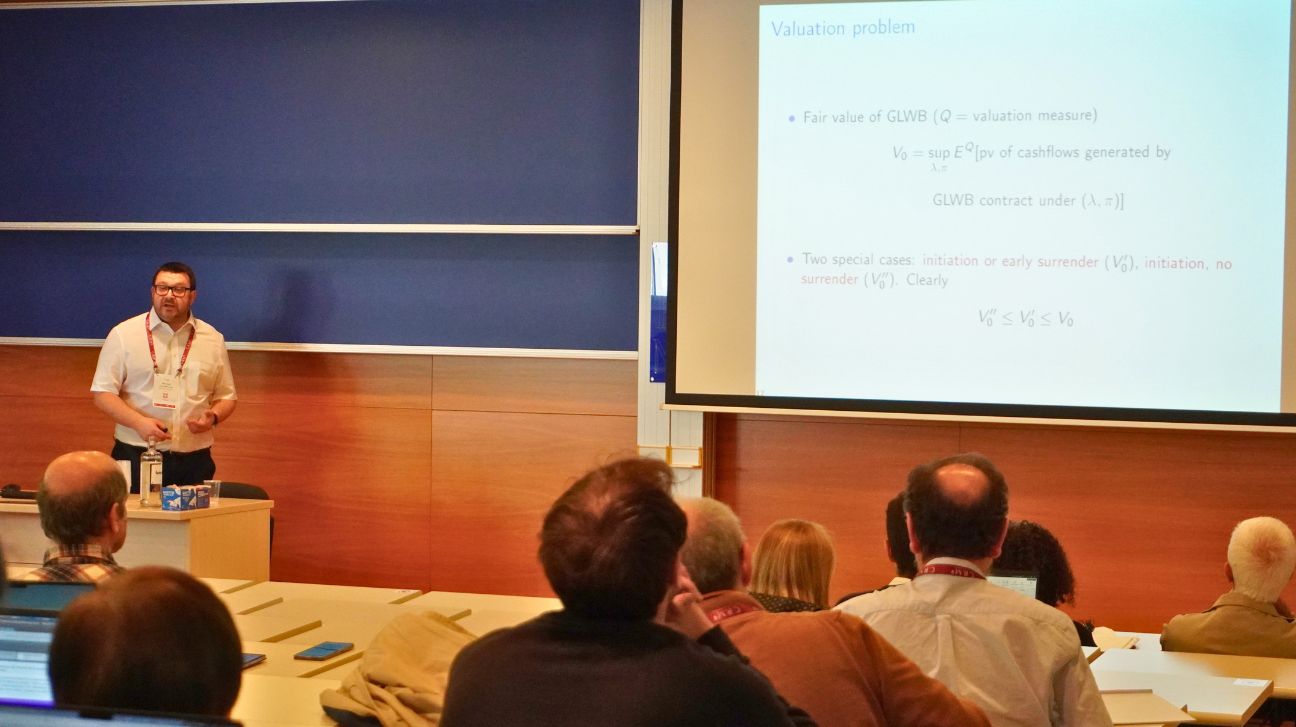
On Friday, Pietro Millossovich (Bayes Business School) presented Three Actuarial Applications of an Iterative Least Square Monte Carlo Algorithm. His lecture demonstrated the flexibility of the Least Squares Monte Carlo (LSMC) method for solving complex problems in life insurance and mortality modelling. Through three applications, he illustrated how this approach allows optimal stopping problems to be addressed while significantly reducing computational complexity.
 |
 |
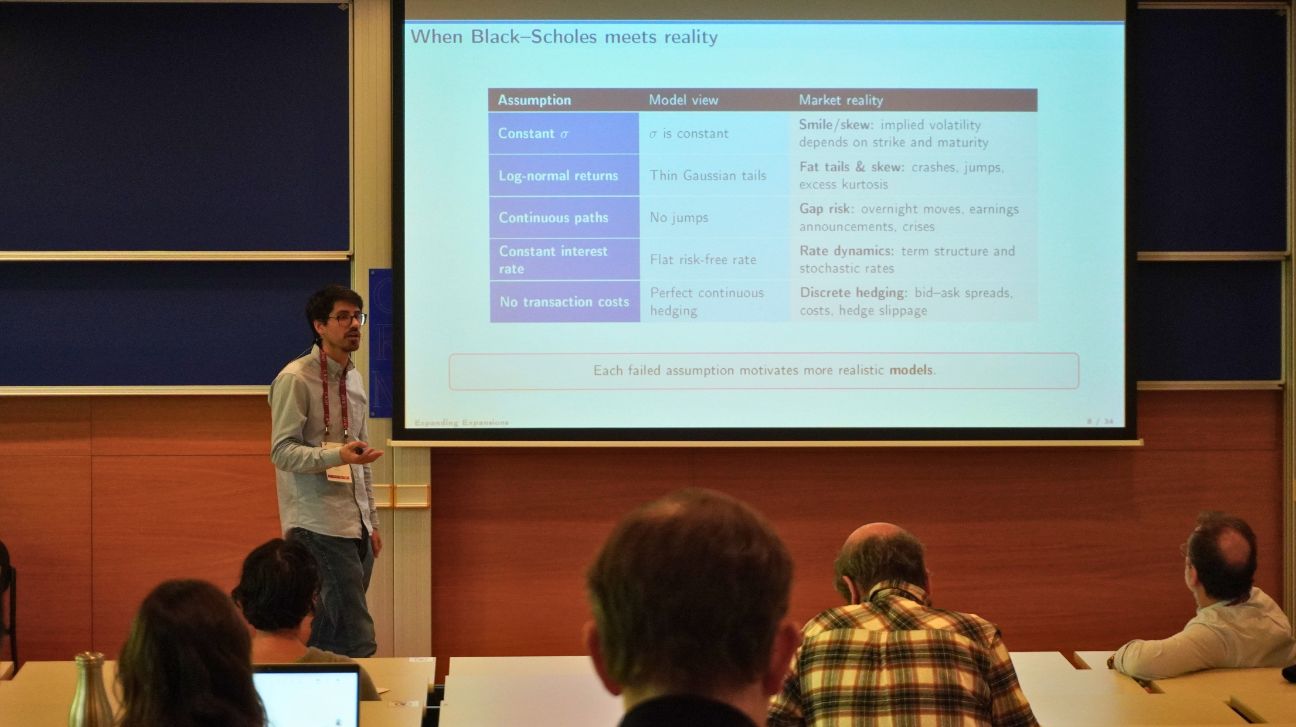
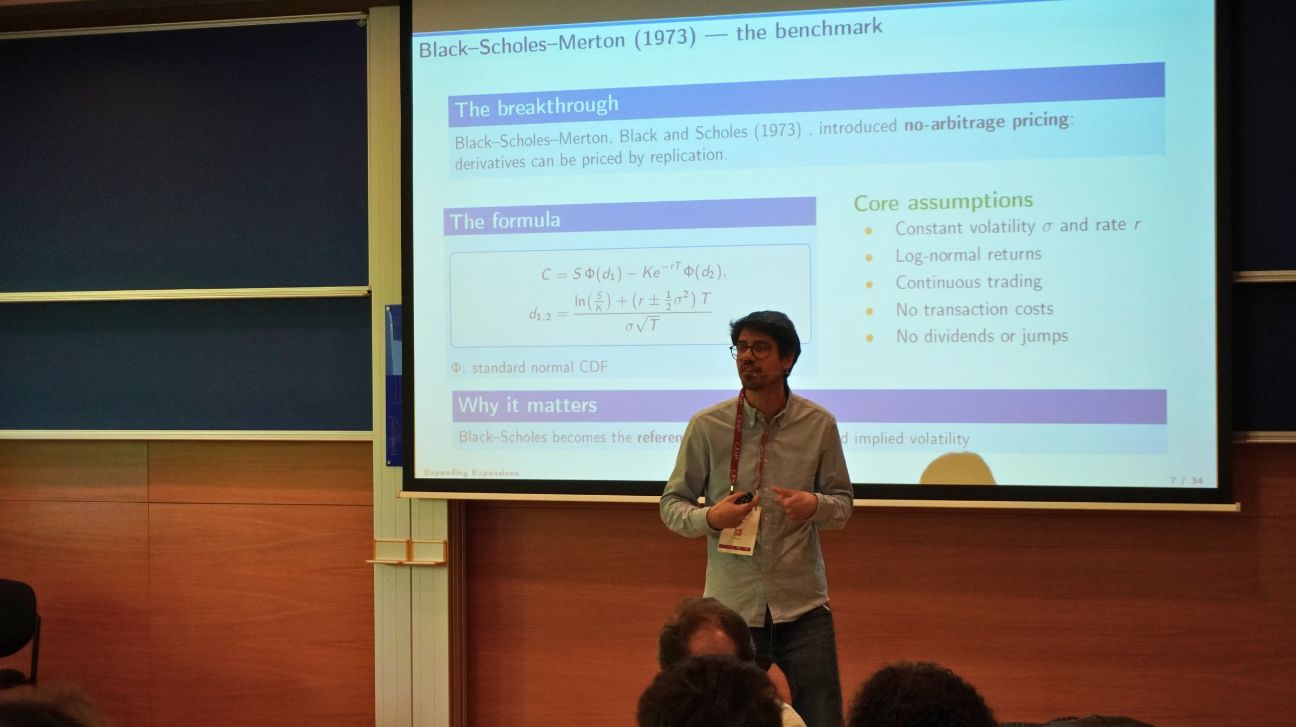
To conclude, Raúl Merino (VidaCaixa), in Expanding Expansions: Beyond Vanillas, reviewed classical expansion methods in quantitative finance and showed how they can be applied beyond so-called vanilla products, i.e. standard financial instruments with simple structures such as basic options or bonds. His talk focused especially on interest rate markets and, using Malliavin calculus techniques, presented approximations capable of systematically capturing convexity effects.
 |
 |
Parallel Sessions and Thematic Areas
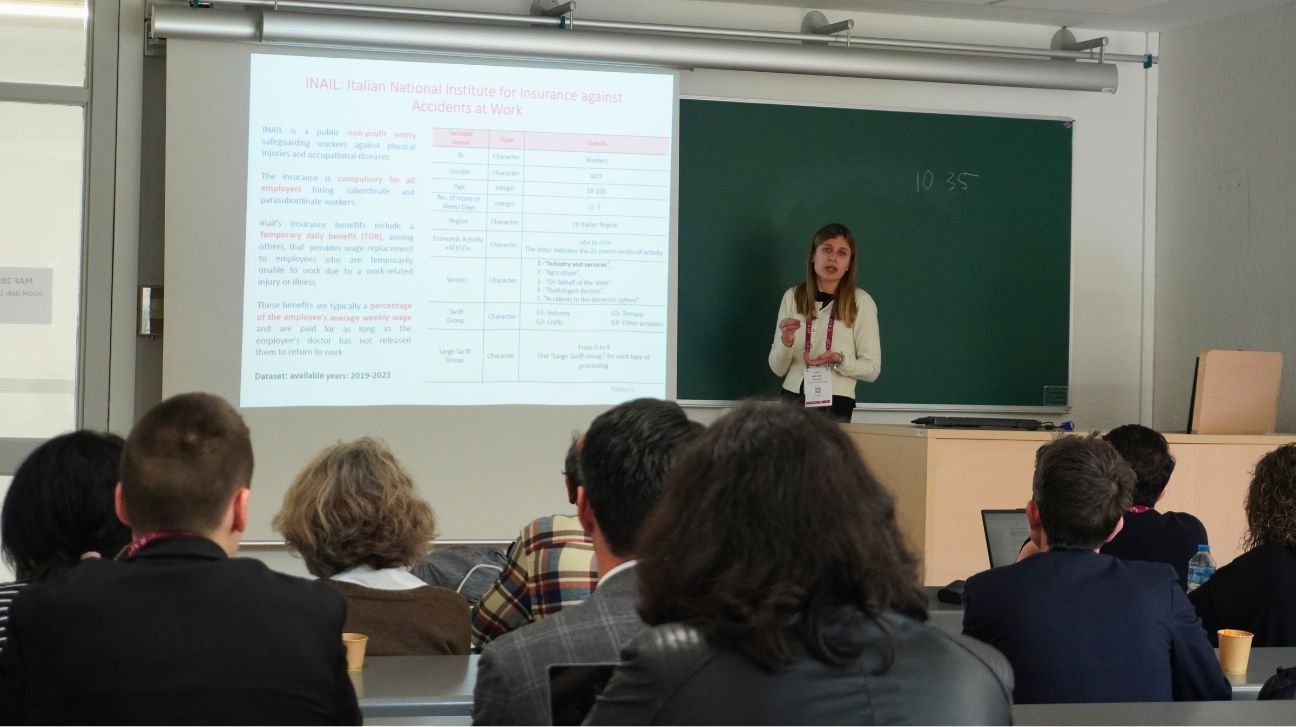
In addition to the plenary lectures, MAF 2026 was structured around parallel and online sessions organised into eight major thematic areas, reflecting the main current research directions in actuarial sciences and finance:
- Climate Risks and Sustainable Finance (ESG), focused on climate risks, energy transition, natural disasters, and sustainable finance.
- Longevity, Health, and Pension Systems, devoted to population ageing, mortality, and the design of sustainable pension systems.
- Machine Learning and Artificial Intelligence, featuring work on model validation, algorithmic biases, and advanced applications in finance and insurance.
- Actuarial Pricing and Count Models, focused on statistical models for pricing and reserving in non-life insurance.
- Financial Networks, Contagion, and Dependence, addressing systemic interconnections, financial contagion, and dependence modelling.
- Portfolio Management and Investment Decisions, dedicated to portfolio optimisation and risk management.
- Financial Mathematics, centred on theoretical models for the valuation of derivatives and complex financial products.
- Actuarial Mathematics, with contributions on actuarial valuation, risk, mortality, and insurance contracts.
 |
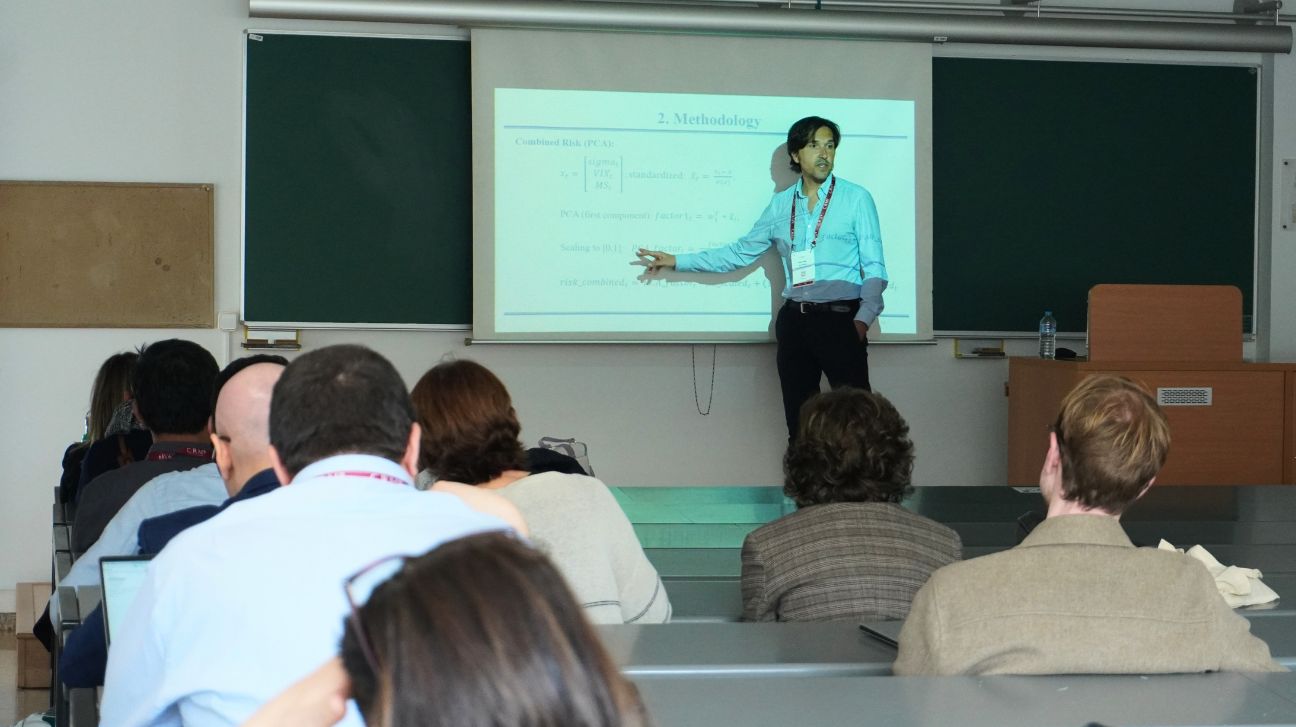 |
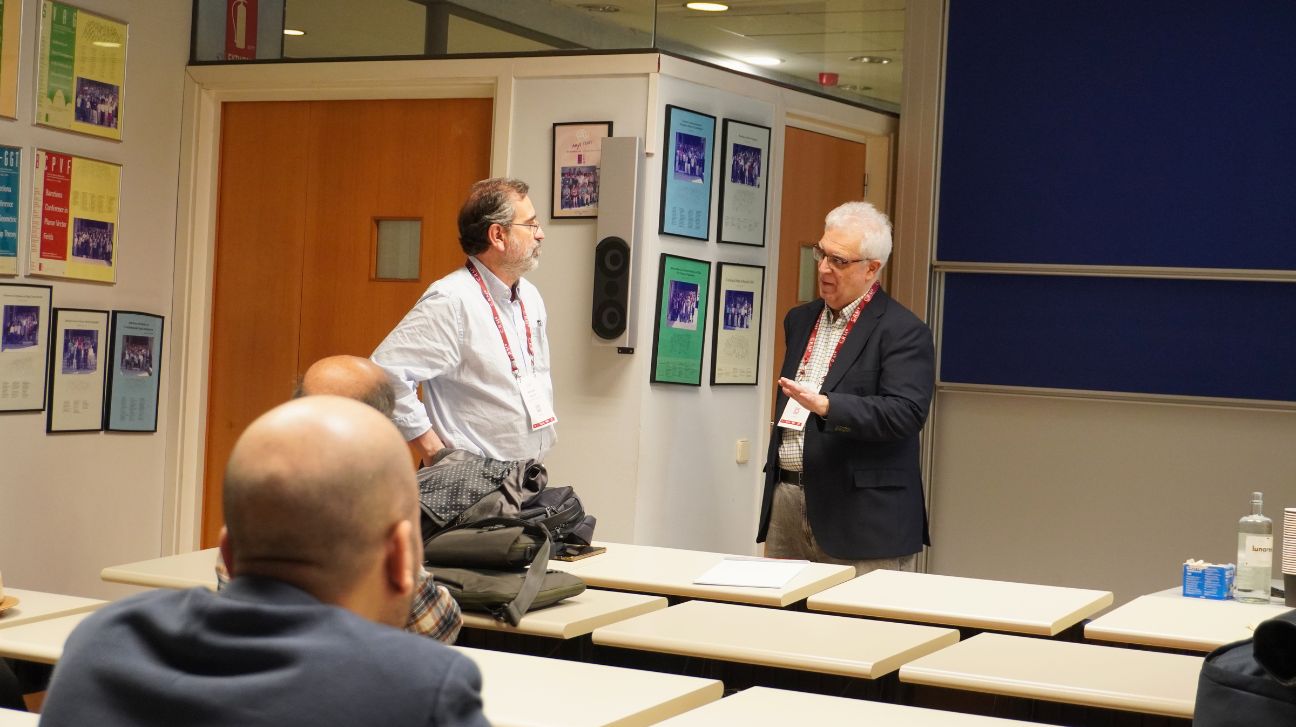 |
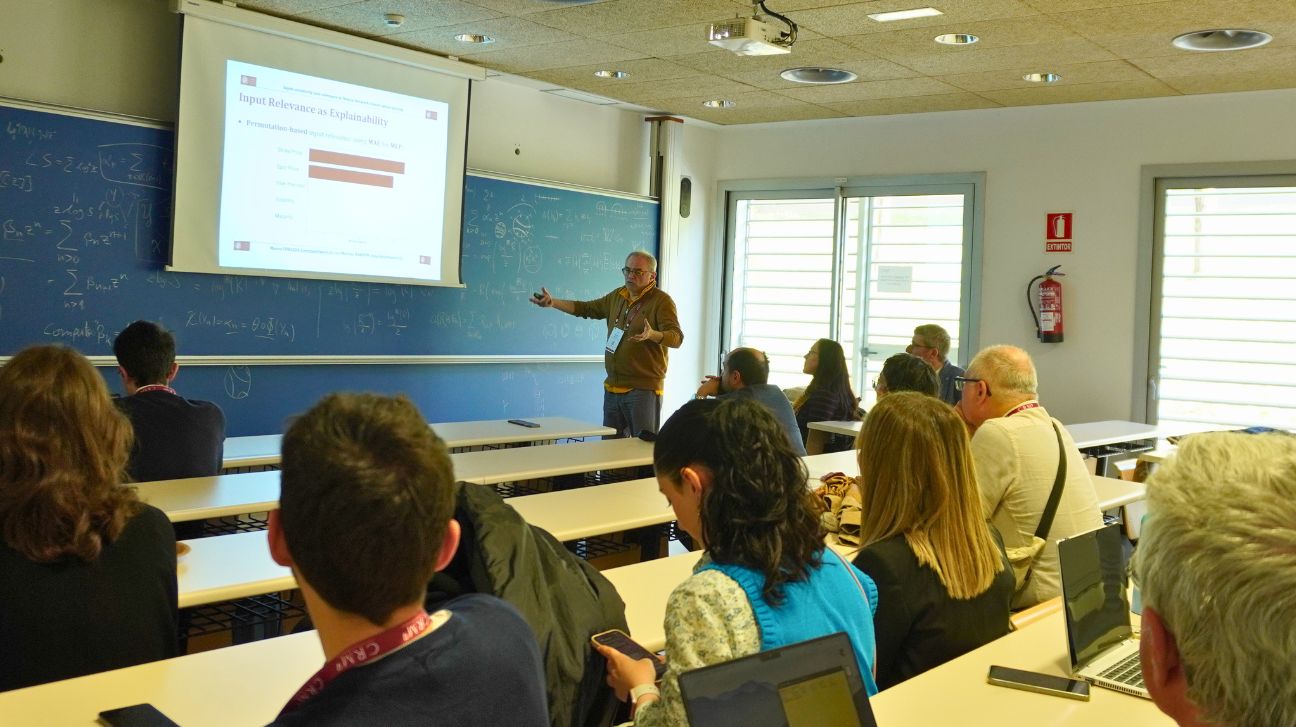 |
An Interdisciplinary Meeting Space
Over the course of three days, the CRM, through MAF 2026, showcased how methodological and theoretical advances can be translated into useful tools to address some of today’s major economic and social challenges, ranging from climate change to population ageing and the digital transformation of the financial sector.
|
|
CRM CommNatalia Vallina
|
Jagged walls and unknown edges: a workshop on free boundary problems
From 2 to 6 November, the Workshop on Free Boundary Problems brought together more than fifty registered participants from institutions in eleven countries at the CRM. Over five days they heard 21 talks on elliptic and parabolic free boundaries and on geometric measure theory and harmonic analysis in rough domains, with speakers including Guy David, Svitlana Mayboroda, Susanna Terracini and Robin Neumayer. The workshop was the second intensive week of the Intensive Research Programme on Analysis of Free Boundary Problems, which continues at the CRM until 4 December.
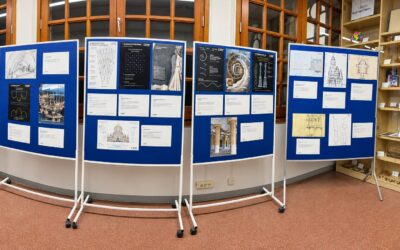
The CRM exhibition ‘Les matemàtiques de Gaudí’ moves to the University of Barcelona
After its October run at the UAB, the exhibition Les matemàtiques de Gaudí, produced by the CRM, can be seen at the University of Barcelona’s CRAI Biblioteca de Matemàtiques i Informàtica from 2 to 30 November 2026.
Advanced Course on Free Boundary Problems Opens the Intensive Weeks of the IRP
From 26 to 30 October, around forty researchers attended the Advanced Course on Free Boundary Problems at the CRM, three seven-hour mini-courses given by Bozhidar Velichkov (Università di Pisa), Max Engelstein (University of Minnesota) and Zihui Zhao (Johns Hopkins University). The course was the first of the two intensive weeks of the Intensive Research Programme on Analysis of Free Boundary Problems, which runs until 4 December.
El CRM rep els estudiants de la prova de nivell de Bojos per les Matemàtiques 2027
Els aspirants a Bojos per les Matemàtiques 2027 van visitar el Centre de Recerca Matemàtica (CRM) dissabte 24 d’octubre, després de fer la prova de nivell a la Facultat de Ciències i Biociències de la UAB. En acabat, Tomás Sanz (UB-CRM) els va explicar què té a veure l’escalfament d’una barra de ferro amb els àudios de WhatsApp.
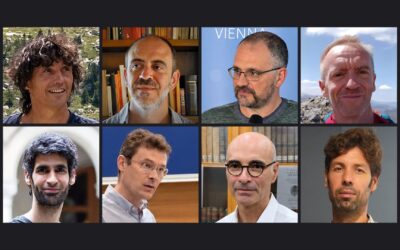
Eight CRM Researchers in the 2026 Stanford-Elsevier List of Highly Cited Scientists
The Centre de Recerca Matemàtica (CRM) has eight researchers in the 2026 update of the Stanford-Elsevier ranking of highly cited scientists, which John P. A. Ioannidis (Stanford University) and Jeroen Baas (Elsevier) compile from Scopus data. Xavier Cabré, Álvaro Corral, Tim Myers, Xavier Ros-Oton, Sergey Tikhonov and Xavier Tolsa appear both in the career-long ranking and in the one for 2025, and Diego Vidaurre and Simeon Ball in the 2025 ranking.
Fish schools and growing tissues: a workshop on how collective behaviour emerges
The Centre de Recerca Matemàtica (CRM) organised the Barcelona Workshop on Kinetic and Macroscopic Models in Biology with Friends II, held from 7 to 10 September at the Institut d’Estudis Catalans. More than thirty researchers discussed how order at the scale of tissues and animal groups arises from local interactions between individuals, in a programme that included talks by CRM researchers Daria Stepanova and Juan Arellano-Tintó. Two of the speakers, James Sharpe (EMBL Barcelona) and Chiara Villa (CNRS, Université Paris Cité), talked to the CRM about their research.
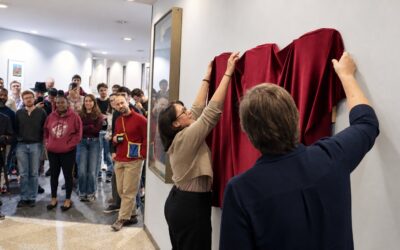
The CRM opens the academic year and unveils its Directors’ Gallery
A review of the year, the Communication Plan 2026–2030 and three research talks filled the morning of 19 October.The unveiling of the Directors’ Gallery.CRM CommPau VarelaCRMComm@crm.catGet the latest CRM news and activities in your inbox.Recent...
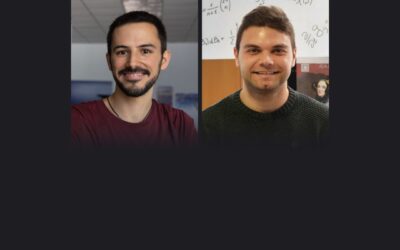
The CRM Mentoring Programme, as Told by One of Its Pairs
PhD student Joaquim Duran and mathematician Robert Cardona, one of the pairs in the CRM Mentoring ProgrammeJoaquim Duran (left) and Robert Cardona.CRM CommPau VarelaCRMComm@crm.catGet the latest CRM news and activities in your inbox.Recent...
When the reward comes within reach, the brain changes what it compares
As the tokens piled up, choices got faster and more accurate at the same time. The yardstick for judging each offer had moved.CRM CommPau VarelaCRMComm@crm.catGet the latest CRM news and activities in your inbox.Recent newsletters →Two subjects...
Almost every automaton can be reset with a short word
Guillaume Chapuy (Université Paris Cité, CNRS) and Guillem Perarnau (UPC, CRM) have shown that a random finite automaton with n states can, with high probability, be reset by a word of length of order √n log n. The result, published in ACM Transactions on Algorithms, pins the exponent at 1/2, the lower end of a decade of numerical estimates, and addresses the random version of the synchronization problem behind a conjecture Ján Černý posed in 1964 and which still remains open.
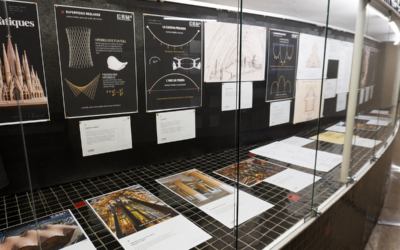
Exposició ‘Les matemàtiques de Gaudí’